Silver has a sixth deficit and a small surplus at the same time
Investors selling out of silver funds covered this year's shortage, but since June they have been buying again, and that takes away the cushion that kept the shortage from showing.
That shortfall is real. Metals Focus and the Silver Institute published their interim review on November 12. It forecasts a sixth deficit in a row, of 35 million ounces (Moz). Silver funds sit outside that figure. They are expected to release 45 Moz over the year, more than the deficit itself. So once fund selling is counted, the market shows a small surplus of 10 Moz. For this year, that is bad for the argument that silver is running short. The review says the narrower shortfall and the metal released by fund selling have helped ease tightness in the physical market. The better news for holders is that most of the selling came early. Since the end of June, funds have bought back 24 Moz. Whether that buying lasts is now the main thing to watch.
On the morning of November 13, silver traded near $49.70 an ounce. Gold was near $3,888.50. That puts the gold-silver ratio at about 78, meaning one ounce of gold buys about 78 ounces of silver. Silver is down about 31% from its 2025 close. This week a hotter US inflation report pushed the dollar to a 19-month high, and precious metals fell with it. The latest premium issue at Golden Meadow® flagged the interim review as the next test of the shortfall argument, mainly because of fund flows.
There are six Deep Dives in this issue of the premium Silver Catalyst newsletter, and in this article, I'll focus on one of them.
How the survey counts
Silver funds, known as exchange-traded products or ETPs, hold physical metal on behalf of their shareholders. When investors buy shares, the fund buys silver. When they sell, the fund releases it.
The survey from Metals Focus and the Silver Institute keeps those funds out of its main balance. The deficit compares the year's supply, mostly from mines and recycling, with demand from industry, photography, jewellery, silverware, and coins and bars. Fund buying sits on a separate line below it. A second balance, called "market balance less ETPs," then adds the fund line. That second balance shows how much metal the year needs from the world's other stockpiles.
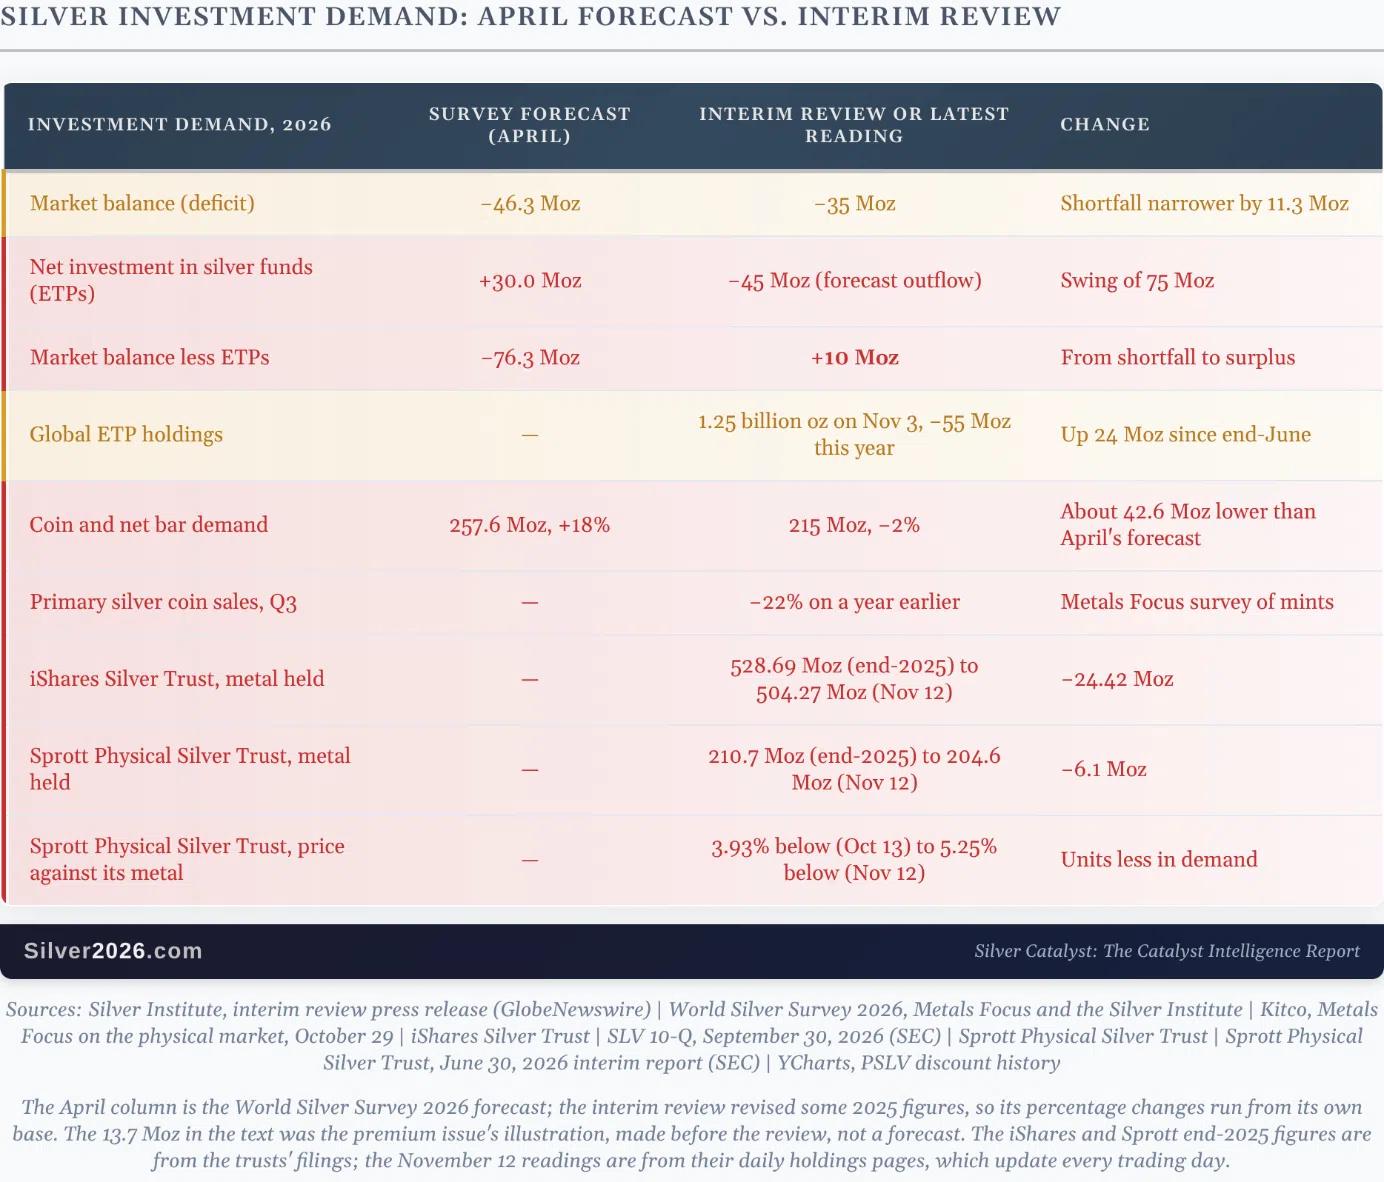
In April, the survey expected funds to add 30 Moz this year. The deficit was 46.3 Moz, so the second balance showed a shortfall of 76.3 Moz. The year was expected to draw on stockpiles.
What changed
Ready to take your investment knowledge to the next level?
Join our community and read the latest analyses and groundbreaking opinions from market experts. Gain exclusive access to valuable insights, engage in thought-provoking discussions, and stay on top of what’s trending in the financial markets.
The funds went the other way. By November 3, global fund holdings were down 55 Moz since the start of the year. They stood at 1.25 billion ounces. Metals Focus now expects net outflows of 45 Moz for the full year. The deficit also narrowed, to 35 Moz.
Put together, the second balance has flipped. It has gone from a shortfall of 76.3 Moz to a surplus of 10 Moz. In plain terms, fund selling is expected to supply more metal than the deficit needs. The survey had seen this risk coming. In April it pointed to the large fund inflows of the past two years and those it expected this year. It said they "could also provide a potential overhang in the market." That means metal that could return to the market later. This year, some of it did.
The premium issue, written before the review, worked through the same arithmetic. It estimated a surplus of about 13.7 Moz if funds ended the year 60 Moz lower and every other line held. The review's own figure is 10 Moz.
Coin and bar buyers also pulled back. The review now expects coin and bar demand of 215 Moz this year, down 2%. In April the survey had forecast 257.6 Moz, a rise of 18%. US retail investment is expected to reach its lowest level since 2010. New coins fell further. Metals Focus surveys the leading mints, and it found sales of primary silver coins, the bullion coins mints sell to investors, fell more than 80% in the second quarter from the first. In the third quarter they were still 22% below a year earlier.
Silver has a sixth deficit and a small surplus at the same time
Sources: Silver Institute, interim review press release (GlobeNewswire) | World Silver Survey 2026, Metals Focus and the Silver Institute | Kitco, Metals Focus on the physical market, October 29 | iShares Silver Trust | SLV 10-Q, September 30, 2026 (SEC) | Sprott Physical Silver Trust | Sprott Physical Silver Trust, June 30, 2026 interim report (SEC) | YCharts, PSLV discount history
The April column is the World Silver Survey 2026 forecast; the interim review revised some 2025 figures, so its percentage changes run from its own base. The 13.7 Moz in the text was the premium issue's illustration, made before the review, not a forecast. The iShares and Sprott end-2025 figures are from the trusts' filings; the November 12 readings are from their daily holdings pages, which update every trading day.
Who is buying again
The selling was not one-way. The review says fund holdings have recovered 24 Moz since the end of June, partly reversing the first-half outflows. It adds that buying has been uneven, and that higher bond yields have held the recovery back.
The two largest physical silver funds are both still below where they started the year. The iShares Silver Trust holds about 24.42 Moz less than at the end of 2025. The Sprott Physical Silver Trust holds about 6.1 Moz less. Sprott's units also trade further below the value of the metal they hold, which suggests investors are not rushing back.
India is a partial bright spot. Bar and coin buying there is still expected to fall 10% this year. But the review says a modest recovery has been under way since June, as prices steadied.
What this means to Silver investors
Silver's shortfall argument rests on the idea that the world uses more silver than it produces, so stockpiles have to make up the difference. Leaving the funds aside, that is still true. The market is heading for its sixth deficit in a row.
This year, though, investors selling their fund holdings filled the gap. Funds that bought heavily in 2025 released metal this year as the price fell. The review says that metal, together with the narrower shortfall, has helped ease tightness in the physical market. For 2026, that is a clear negative for the shortfall argument. The reverse also holds: when investors buy, funds take metal out of the market, and the shortage shows again. A shortage that shows is good news for silver holders, because buyers who cannot find enough metal tend to bid the price up.
The question for a holder is whether the selling has run its course. Holdings have been rising since June, and the deficit is narrower but intact. If fund buying holds up, funds stop releasing metal to the physical market, where manufacturers, jewellers and coin makers buy their silver. The deficit would then again have to be met from stockpiles. If rising yields keep investors away, funds can keep selling metal into that market. The longer-term case depends on which of those wins, and so far this year the outflows have won.
Want free follow-ups to the above article and details not available to 99%+ investors? Sign up to our free newsletter today!
Author

Przemyslaw Radomski, CFA
Gold Price Forecast
Przemyslaw Radomski, CFA (PR) is a precious metals investor and analyst who takes advantage of the emotionality on the markets, and invites you to do the same. His company, Sunshine Profits, publishes analytical software that any

















