|

Asia week ahead: Japan GDP and key data from China and Taiwan

China: Domestic weakness persists as IP outperforms

China releases its key domestic activity data for October on Monday. After a surprisingly solid September, we expect retail sales growth to moderate to 0.7% YoY as consumption stays soft amid weak discretionary consumption. After stabilising last month, fixed asset investment growth could see a smaller drag in October as public investment picks up. We expect headline FAI to rise to -6.7% YoY YTD.

Industrial production is expected to remain the outperformer, and we think growth will remain unchanged at 5.5% YoY. We will also watch the 70-city property price data, which has recently been showing a stabilisation of prices in tier 1 and a few tier 2 cities. Later next week, China’s loan prime rates will be released, with the 1- and 5-year LPRs expected to remain unchanged at 3.0% and 3.5%, respectively.

Taiwan: Export orders continue to grow

Taiwan releases its export orders data next Friday. We expect the strong growth of the past few months to continue and are looking for 67.0% YoY growth in October. This indicator is worth watching closely for signs that the AI capex cycle could be slowing, but so far we haven't seen any such signal. Various Taiwanese corporates have signalled that order books remain full on an 18-month rolling basis, suggesting that momentum should stay solid for now.

Japan: Third quarter GDP and activity data in focus

Japan will release its Q3 GDP and trade data next week. The market expects growth to slow sharply to 0.1% QoQ from the previous 0.4%, with private consumption contracting 0.2% as the expiry of energy subsidies pushed utility bills sharply higher. Markets expect imports to accelerate to 25.9% YoY on energy and capital equipment, while exports pick up to 20.1%, extending to 13 consecutive months of YoY gains. Altogether, it leads to a trade balance deficit of JPY1067bn.

Japan will also release its inflation data next Friday. The market expects headline inflation to accelerate to 2.5% YoY from 2.1% in September with core CPI rising to 2.3%. A firm inflation reading would support expectations for further Bank of Japan policy normalisation.

Key events in Asia next week
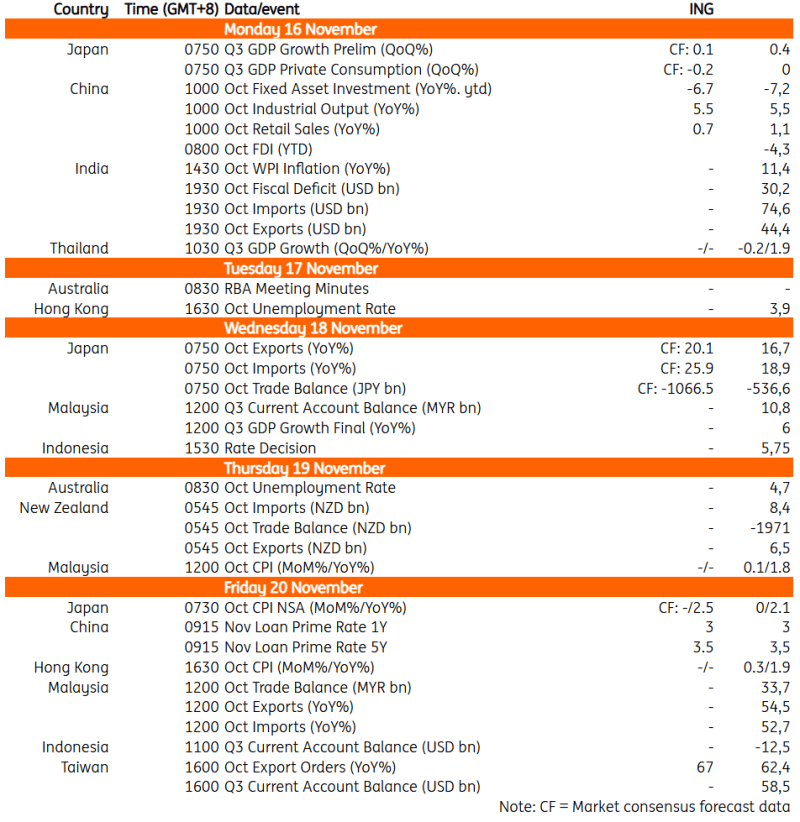
Chart

Read the original analysis here

Author

ING Global Economics Team

ING Global Economics Team

ING Economic and Financial Analysis

From Trump to trade, FX to Brexit, ING’s global economists have it covered. Go to ING.com/THINK to stay a step ahead.


More from ING Global Economics Team
Share:

Editor's Picks

AUD/USD seems vulnerable near 0.6800, 10-month low amid bullish USD

AUD/USD languishes near a 10-month low during the Asian session on Friday, awaiting a break below 0.6800 before the next leg up amid a bullish US Dollar. Firming Fed rate-hike expectations, along with fading hopes for US-Iran diplomacy, help the USD hold gains at its highest level since April 2025. Moreover, the RBA’s dovish tilt undermines the Aussie and backs the case for further losses.

USD/JPY bulls turn cautious near 160.00 amid intervention risks

USD/JPY enters a bullish consolidation phase around its highest level since early September as bulls turn cautious amid intervention risk near 160.00. Meanwhile, the downside seems cushioned as the wide US-Japan interest rate gap keeps the Yen carry trade active. Furthermore, the possibility of a jumbo Fed rate hike and Middle East uncertainties hold the US Dollar near a 19-month top, supporting the currency pair.


Gold sticks to gains above $3,900; bulls lack conviction as Fed and Iran risks support USD

Gold clings to modest recovery gains above the $3,900 mark during the Asian session, snapping its three-day losing streak to the lowest level since late September set the previous day. The US Dollar takes a breather after a strong three-day rally to its highest level since April 2025, offering some support to the commodity. However, firming US Federal Reserve rate-hike expectations and Middle East uncertainties continue to support the Greenback. This keeps a lid on any further upside for the precious metal.

Bitcoin just posted five straight losing weeks, and the storm may not be over yet

Bitcoin is struggling to find support, slipping below $70,000 as multiple headwinds threaten to push the Crypto King lower. The much-anticipated “Uptober” rally failed to materialize, with persistent selling pressure and widespread liquidations instead reinforcing the “Rektober” narrative.

Week ahead – Fed Minutes, inflation data and Nvidia earnings to guide investors

Fed minutes may add to hawkish tone as bets of 50-bps hike grow. Nvidia to report earnings as bar to impress high after spy scandal. Trade and geopolitics to be focal point of Trump-Xi summit.

What the US CPI headline doesn’t tell you about inflation

Brent crude has fallen about a third since mid-October on hopes the Iran war is ending, but diesel, freight and fertiliser costs haven't followed. Those costs reach US consumer prices in stages through 2027 and could keep inflation high after gasoline gets cheaper.














