United States Dollar Index weakens further amid correction in US bond yields
- The US Dollar Index declines further to near 102.02 as US Treasury Yields retreat.
- US President Trump confirms not attacking Iran before Mid-term elections.
- US CPI data will be key trigger next week.
The US Dollar (USD) extends its decline against its major peers on Friday as United States (US) Treasury Yields correct after failing to extend the rally.
US Dollar Price Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the weakest against the Australian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.12% | -0.08% | 0.08% | -0.08% | -0.24% | -0.24% | -0.21% | |
| EUR | 0.12% | 0.05% | 0.21% | 0.04% | -0.11% | -0.08% | -0.10% | |
| GBP | 0.08% | -0.05% | 0.19% | 0.02% | -0.15% | -0.12% | -0.08% | |
| JPY | -0.08% | -0.21% | -0.19% | -0.16% | -0.32% | -0.31% | -0.27% | |
| CAD | 0.08% | -0.04% | -0.02% | 0.16% | -0.19% | -0.16% | -0.11% | |
| AUD | 0.24% | 0.11% | 0.15% | 0.32% | 0.19% | 0.02% | 0.08% | |
| NZD | 0.24% | 0.08% | 0.12% | 0.31% | 0.16% | -0.02% | 0.05% | |
| CHF | 0.21% | 0.10% | 0.08% | 0.27% | 0.11% | -0.08% | -0.05% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
In the Asian trade, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades 0.1% lower to near 102.02. The DXY faced significant selling pressure on late Thursday after failing to extend the rally beyond its yearly high of 102.54 posted earlier this year. 10-year US Treasury Yields have retreated to near 5.23% from its Thursday’s high of 5.35%.
Yields on US-backed securities came under pressure as oil prices cut gains after President Donald Trump ruled out fears of renewed military activities against Iran till Mid-term elections.
“We [US] will not be attacking Iran at any time prior to the Midterm Elections to be held in the United States on November 3rd,” US President Trump said through a post on Truth Social, adding, “We are having productive discussions with the Islamic Republic of Iran.”
Going forward, the major trigger for the US Dollar will be the US Consumer Price Index (CPI) data for September, which will be released on Wednesday. The inflation is expected to have a significant impact on Federal Reserve’s (Fed) interest rate expectations.
Currently, the CME FedWatch tool shows that financial markets have priced in at least one interest rate hike in the remainder of the year.
US Dollar Index Technical Analysis
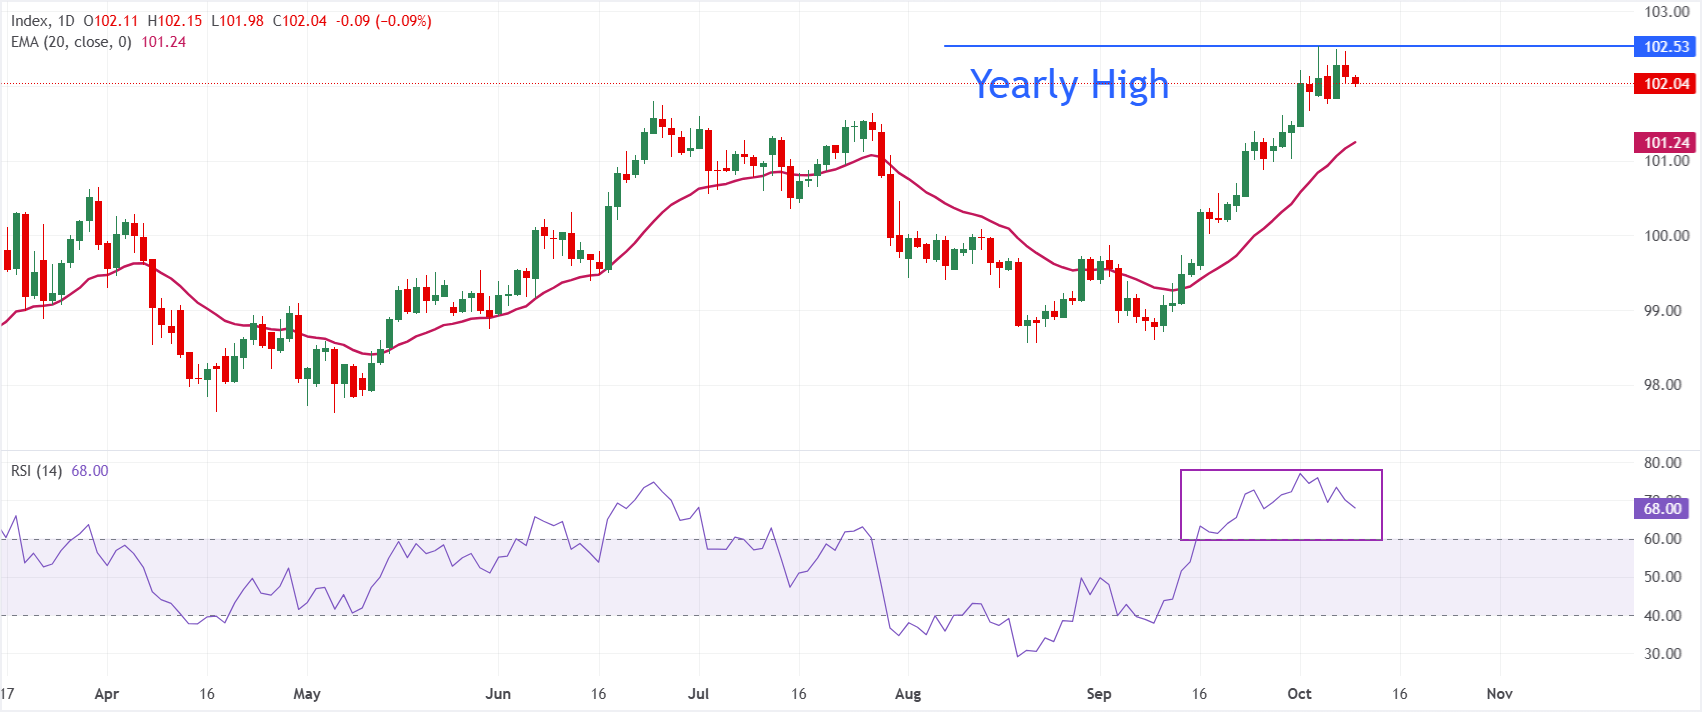
In the daily chart, Dollar Index Spot trades at 102.03, holding above the 20-day exponential moving average (EMA) at 101.24, which suggests a bullish near-term bias with the trend underpinned by dynamic support. The Relative Strength Index (14) at 67.91 hovers just below overbought territory, hinting that upside momentum remains strong but may be entering a more mature phase where further gains could be slower or prone to brief pauses.
On the downside, initial support is located at the 20-day EMA at 101.24, where a decisive break would weaken the bullish structure and open the door to a deeper corrective phase toward prior price congestion zones. Looking up, the yearly high at 102.54 is the major hurdle.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















