The Euro slips as Europe's biggest economies report hotter inflation
- EUR/USD slips to a second straight close under 1.1350 as US yields climb.
- Spain's September inflation at 5%, its highest since 2023.
- Eurozone flash inflation due Friday, forecast at 3.6% from 3.2%.
Germany, France, Italy and Spain all reported September inflation above forecast, which should have lifted bets on another European Central Bank (ECB) hike and the Euro with them. EUR/USD closed lower instead, its second straight close under 1.1350. Spain's rate reached 5%, the highest since 2023, and the currency Spain shares with the other three lost ground to the Dollar on the same releases.
Energy inflation reads as a tax, not a reason to buy the Euro
Most of this inflation comes from energy prices tied to the US-Iran war, and an energy shock raises prices while leaving households less to spend on everything else. The ECB raised its deposit rate to 2.50% on September 10 and decides again on October 29, the day after the Fed.
ECB Executive Board member Schnabel, who is leaving for a senior role at the International Monetary Fund (IMF), said on Wednesday that the recent jump in global yields may damp price pressures and let inflation return to target more gradually. She's usually counted among the ECB members most willing to hike, and her case was that the bond market may do part of the ECB's job. For EUR/USD, tighter money from the bond market does nothing for the rate gap with the US, where the 10-year yield rose on Wednesday to its highest since 2007.
Friday's number is forecast at almost twice the ECB's target
The flash Harmonised Index of Consumer Prices (HICP) for September is due Friday at 09:00 GMT, forecast at 3.6% YoY from 3.2%, with the core rate forecast at 2.5% from 2.4%. ECB President Lagarde speaks on Thursday at 13:30 GMT, and the US payroll count arrives the same Friday at 12:30 GMT.
A hot HICP would raise the October 29 odds, but EUR/USD also has the US jobs count to absorb the same day. It's possible a 3.6% reading lifts the Euro where four national readings above forecast didn't, though Wednesday's close says traders want more than inflation before they buy it.
The Euro's map between two Friday releases
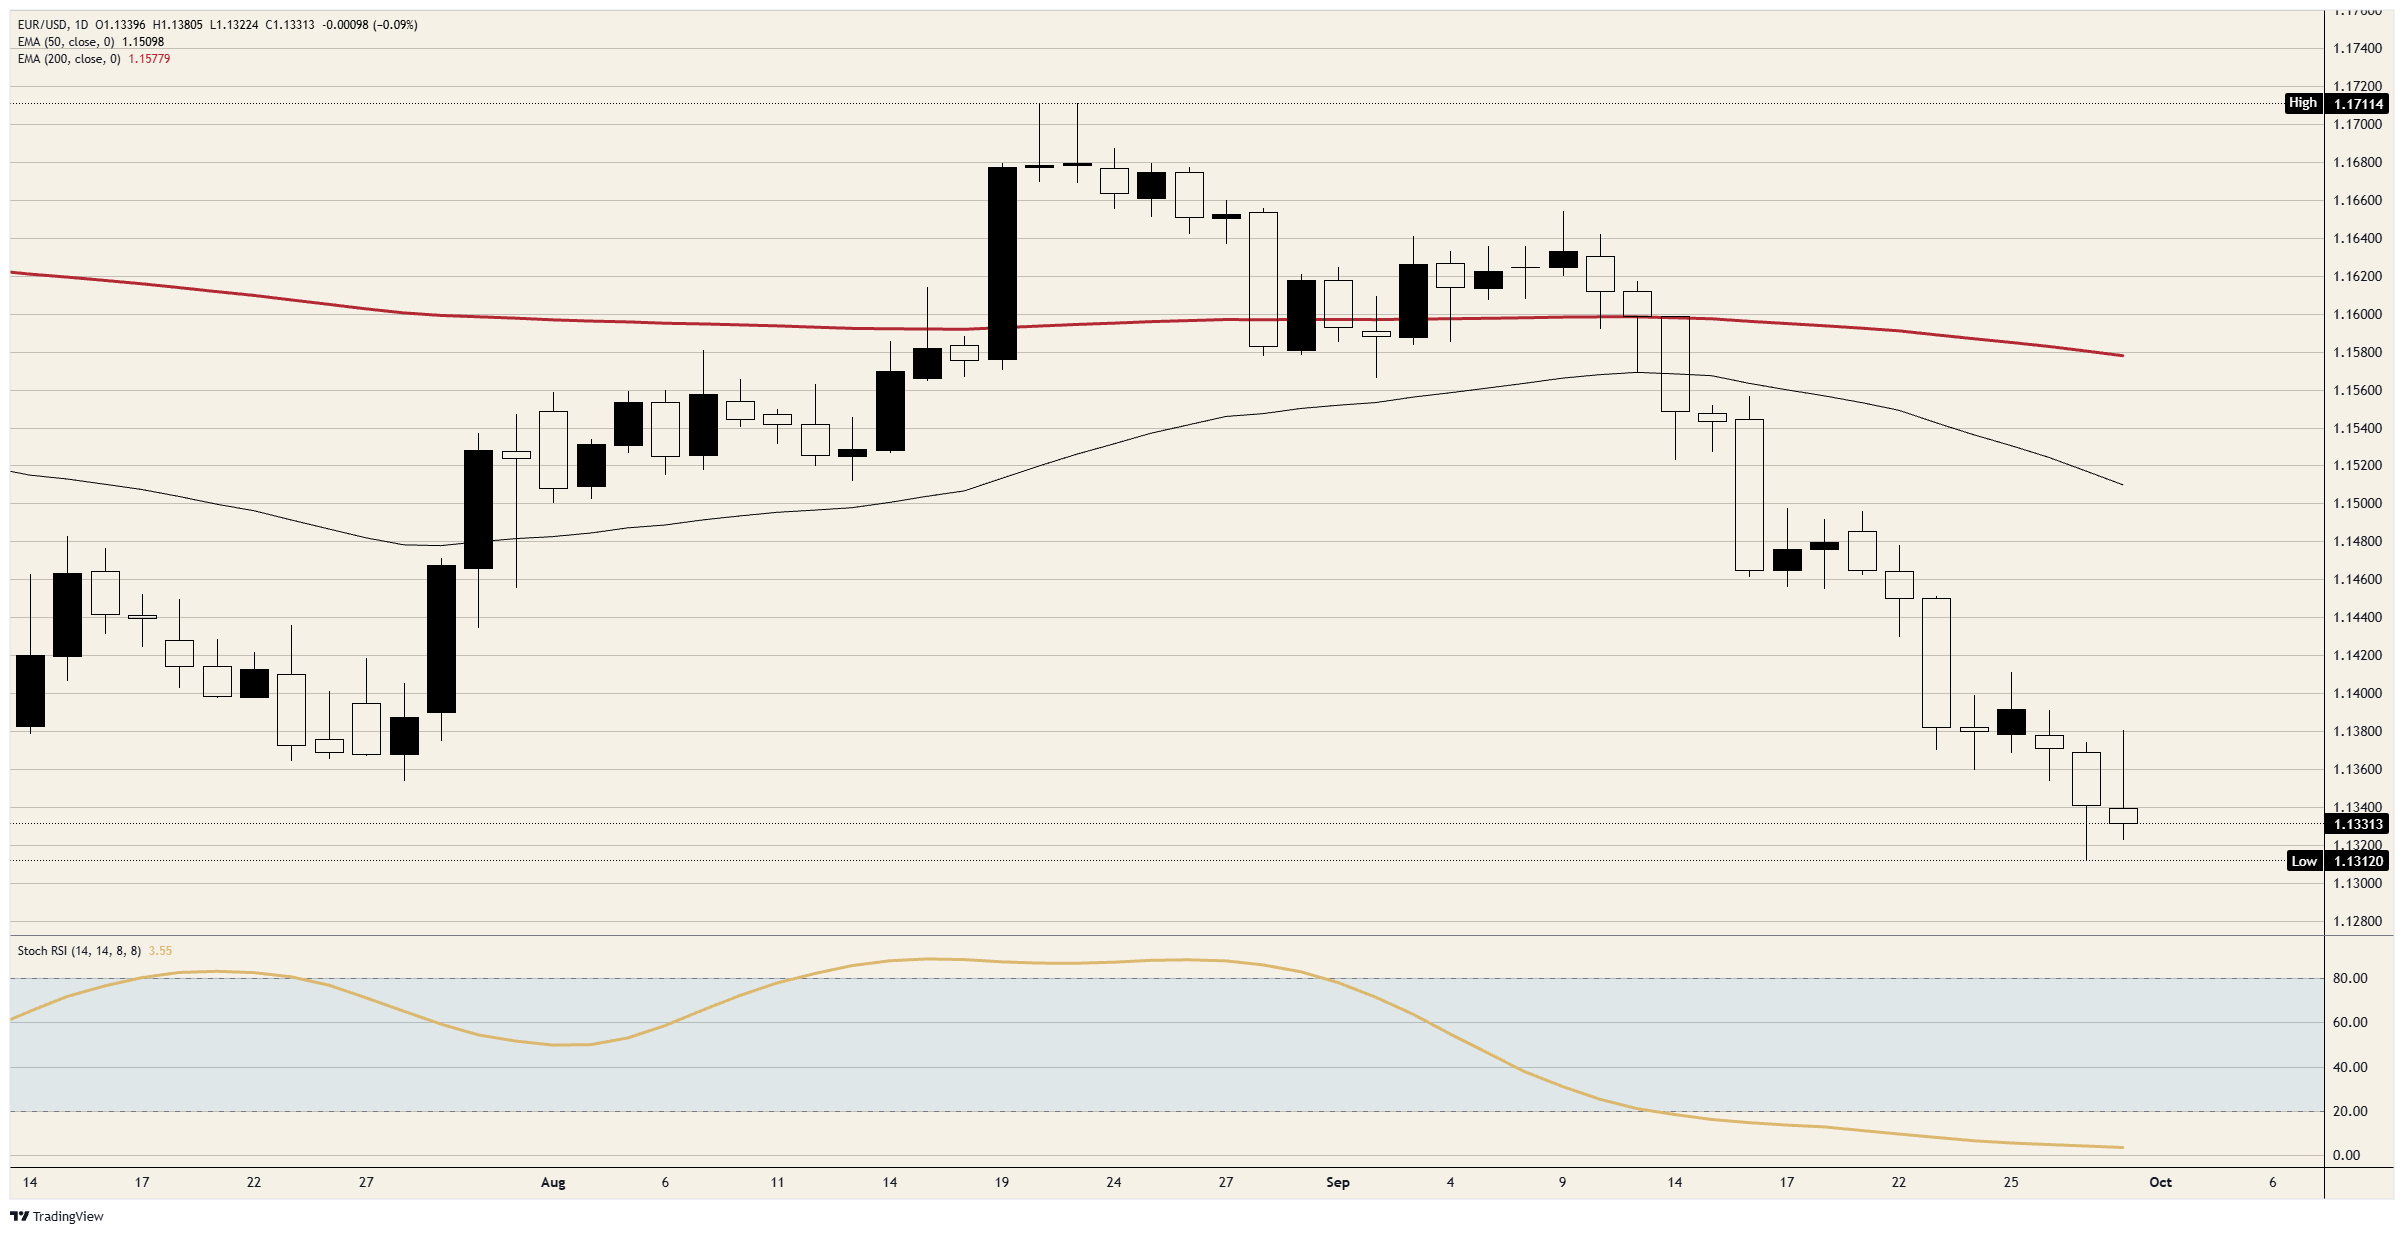
Resistance: 1.1400 has stopped every bounce since the September 23 break, and Wednesday's high came in short of it. 1.1450 is next.
Support: Tuesday's low just above 1.1300 is the lowest since May 2025, and 1.1250 is below it.
Bias: The lean is short under 1.1400, with 1.1300 as the first objective and 1.1250 as the second. With the Stochastic Relative Strength Index (Stoch RSI) on the daily down near 4, about as stretched as it gets, a squeeze toward 1.1400 on Friday's numbers wouldn't end the trade. A daily close above 1.1450 would.
EUR/USD daily chart
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















