"More avenues opening for US Dollar weakness ahead": MUFG on why Treasury buyback could backfire
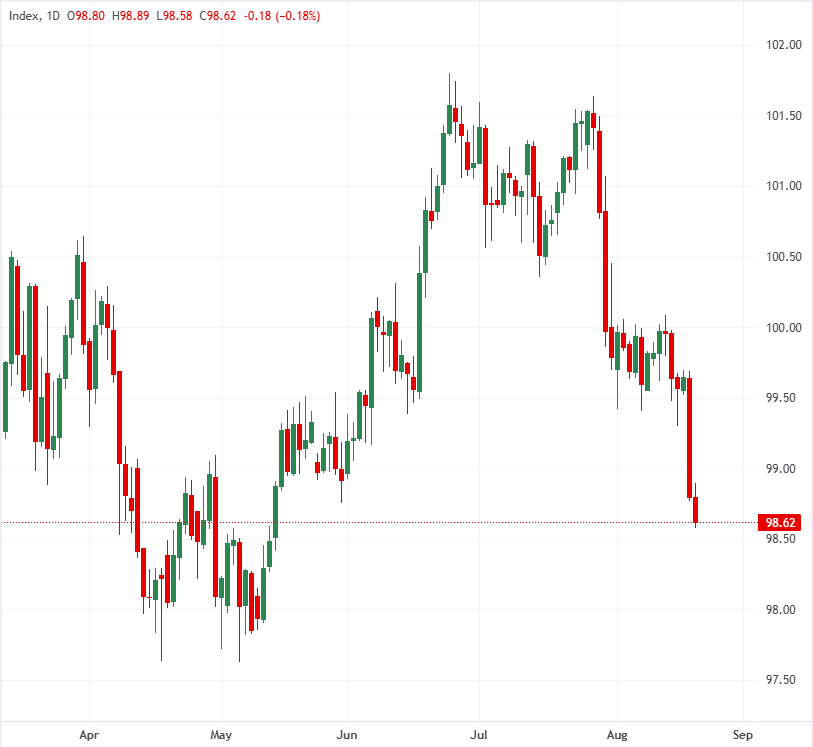
The US Dollar (USD) has extended its decline following the US Treasury’s unexpected decision to double its long-end bond buybacks, an intervention designed to push down long-term borrowing costs. While the announcement initially triggered a sharp rally in Treasuries and pulled 10-year yields down, market focus has rapidly shifted to fiscal credibility.
Institutional analysts across MUFG, UBS, and Brown Brothers Harriman (BBH) warn that using debt swaps to cap long-end yields risks signaling official discomfort with rising borrowing costs, leaving the Greenback increasingly vulnerable to downside pressure.
Unscheduled buyback expansion exposes structural US Dollar vulnerability
According to analysts at MUFG, the Treasury's decision to expand buybacks from $2 billion to $4 billion represents a direct attempt to curb rising long-term yields. However, attempting to manage yields without genuine fiscal consolidation risks alienating global investors and opening up multiple pathways for US Dollar depreciation.
Even if the Treasury buy-back plan does contain yields, the US Dollar now remains more vulnerable to the downside on the fact that yields are potentially lower (...) There appears to now be more avenues opening for US Dollar weakness ahead rather than dollar strength.
Yield intervention aims to mitigate Gulf war and tariff pressures
UBS notes that doubling bond purchases helped ease borrowing costs that were exacerbating the US debt service and affordability crisis. Analysts at the bank suggest the policy acts as an intentional countermeasure against market fallout caused by geopolitical conflicts and tariff measures, though policy uncertainty from the Federal Reserve continues to add an underlying risk premium.
Higher yields impact the US affordability crisis and debt service costs, making them a political focus. This policy is to counter the (presumably unintended) consequences for bond markets of other policies like the Gulf war and tariffs.
Managing yields rather than liquidity erodes fiscal credibility
Strategists at BBH explain that while the buyback acts as a debt-management swap financed by short-term bill issuance, its timing sends a troubling signal. Coming shortly after 30-year yields reached their highest levels since 2007, the operation creates a strong perception that the Treasury is intervening to cap long-end borrowing costs rather than simply improving market liquidity.
The timing of the Treasury’s buyback announcement sends a less comfortable message (...) The perception the Treasury is managing yields rather than liquidity undermines US fiscal credibility and is a drag on USD.
Further US Dollar weakness expected ahead
The Treasury’s expanded buyback program has introduced a structural drag on the US Dollar, the banks say. While UBS highlights the immediate relief provided to bond yields and debt affordability, both MUFG and BBH caution that intervening in long-end borrowing costs erodes fiscal credibility and undermines investor demand for US assets, leaving the dollar firmly biased toward further weakness.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
Author

FXStreet Insights Team
FXStreet
The FXStreet Insights Team is a group of journalists that handpicks selected market observations published by renowned experts. The content includes notes by commercial as well as additional insights by internal and external analysts.