Euro stalls as Fed hike bets offset cooler Eurozone CPI
- US JOLTS rise keeps Fed tightening expectations firmly alive.
- Cooler European inflation data weighs on ECB hike bets.
- NFP report could decide Dollar’s next directional impulse.
The Euro fails to gain traction versus the US Dollar on Tuesday, with the pair remaining steady at around 1.1400 as economic data on both sides of the Atlantic barely moved the needle. The EUR/USD trades at 1.1420.
EUR/USD holds near 1.1400 as Fed and ECB signals diverge
Geopolitical fears are tempered as the US and Iran are set to continue negotiations. Therefore, risk appetite improved as depicted by US equity markets, which ended the first half and the second quarter of the year on a higher note.
Speculation that the Federal Reserve will raise interest rates boosted the Greenback during the session. The US Dollar Index (DXY), which measures the buck’s performance against a basket of six peers, is up 0.06% at 101.17.
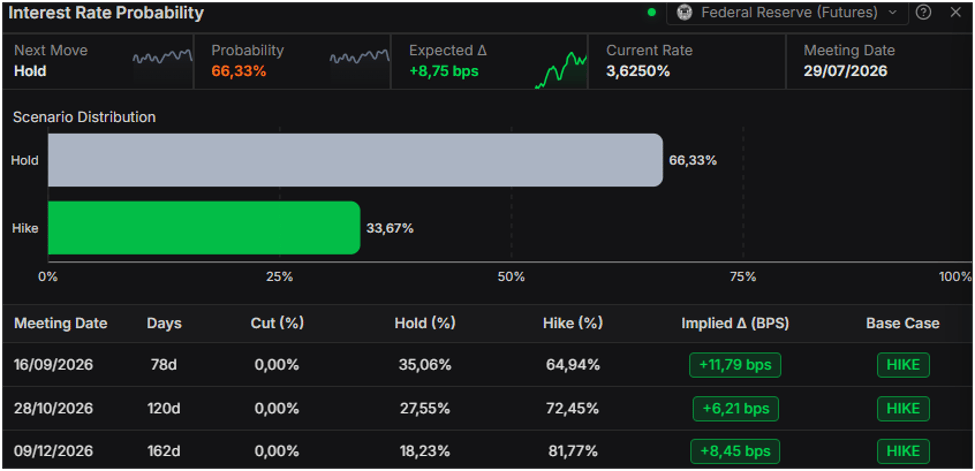
Money markets have so far priced in 35 basis points of policy tightening towards the end of the year, but for the July meeting, there’s a 66% chance of a hold, according to Prime Terminal data. Nevertheless, for the September 16 reunion, there’s 82% chance that the US central bank could hike rates to the 3.75%-4% range.
On Tuesday, the US economic docket revealed that job vacancies unexpectedly jumped in May, with further insights reaffirming the low-hiring, low-firing environment in the labor market. At the same time, the Conference Board Consumer Confidence nudged higher in June, despite Americans becoming worried about the jobs market.
Cleveland Fed President Beth Hammack stated on Tuesday that she might still support higher interest rates if inflationary pressures do not ease.
Thursday's June jobs report is the key US economic event. Three months of strong job gains have reinforced the hawkish stance of the Fed. Economists expect that the economy added 110K jobs in June, with unemployment steady at 4.3%.
ECB expected to hold rates in July
Across the pond, inflation data in France, Italy and Germany were cooler than expected, a headwind for the Euro.
In the meantime, European Central Bank (ECB) officials crossed the wires. The Chief Economist, Philip Lane, said that the bank should not pre-commit to a specific meeting in July or September, but remained vague. ECB’s Dolenc strives for patience and wants to wait until September
Other members, like Kazaks, said that there’s no need for a forceful inflation response, while Nagel said that “it’s too early to call for further rate hikes.” Rehn was neutral, while Wunsch supports another rate hike.
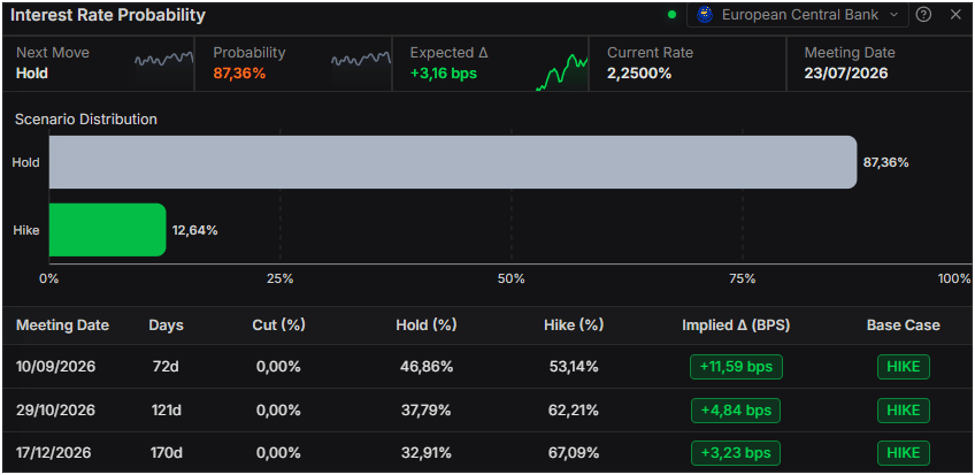
Money markets had priced in a nearly 60% chance of another 25 basis points of rate increases by the ECB at the September meeting. In July, the central bank is expected to hold rates unchanged.
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















