Euro extends its slide as US surveys top Europe's strong reading
- EUR/USD extends its slide to a late-July low as US surveys top Europe's.
- Eurozone composite PMI at 53.1, the highest since April 2023.
- ECB deposit rate at 2.50%, against 3.75-4.00% at the Fed.

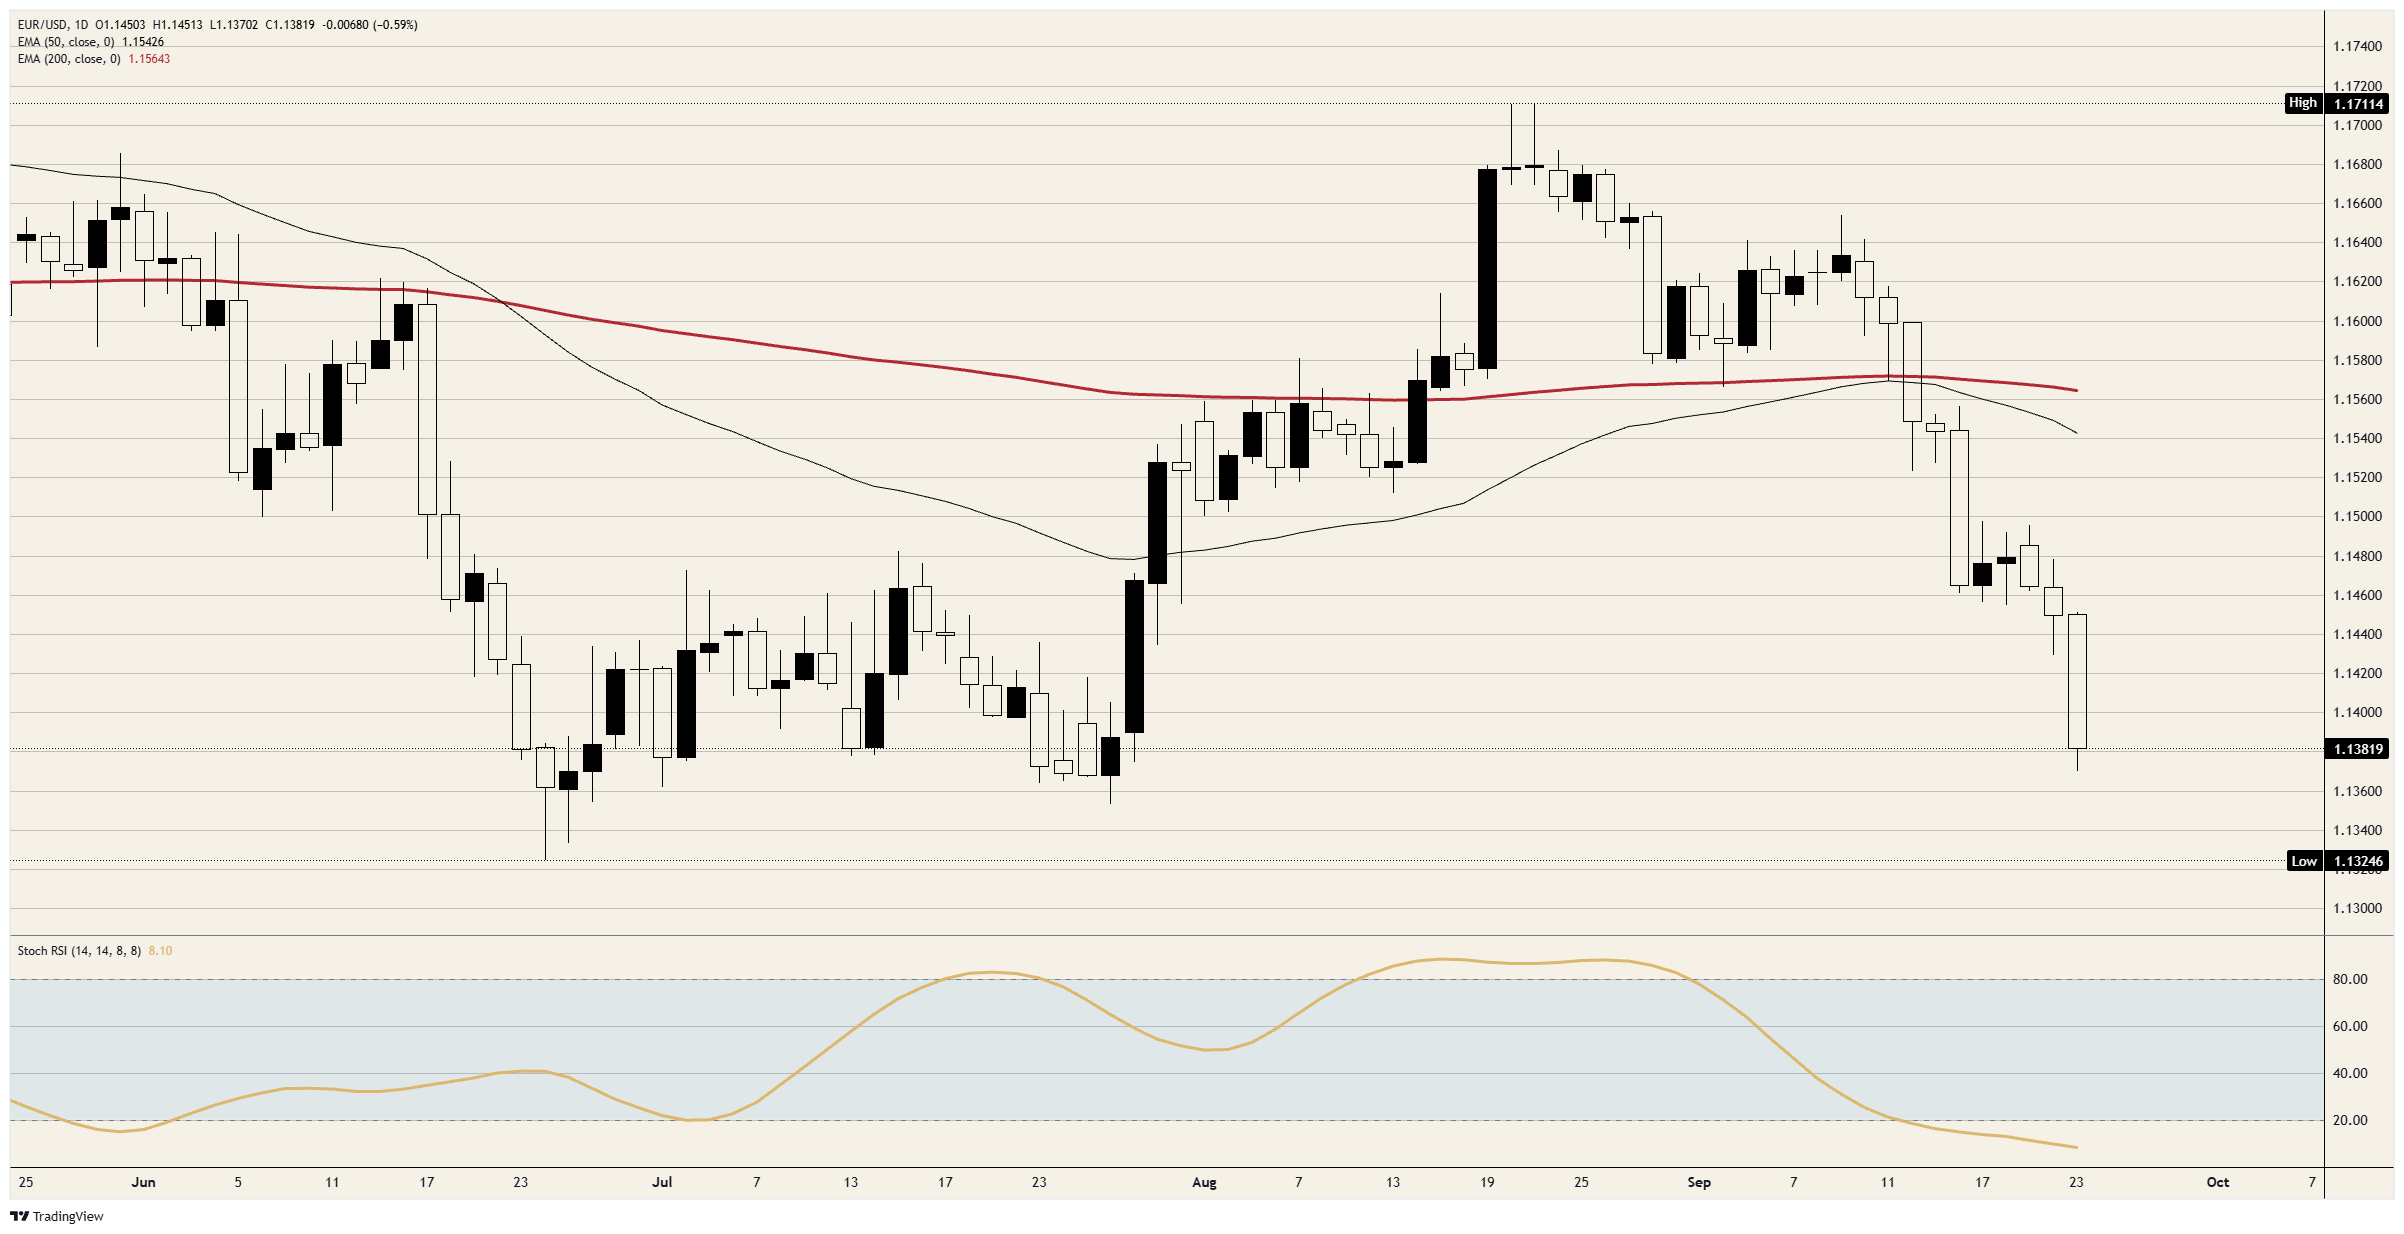
Europe's September business surveys were the strongest since April 2023, and the Euro fell to its lowest since late July on the day they came out. The eurozone's flash Purchasing Managers Index (PMI) composite reading came in at 53.1 against a 51.5 forecast, with services at 53 against 51.7. EUR/USD is trading just under 1.1400, on track for a third losing session in a row.
A good European number lifts the Euro only if it changes what the European Central Bank (ECB) does next, and the ECB has already moved. It raised its deposit rate to 2.50% on September 10, its second increase this year. The US surveys beat their forecasts by even more, and traders added to bets on another Fed increase on October 28.
Five more ECB hikes would only reach where the Fed's rate starts
ECB Executive Board member Schnabel speaks on Thursday at 07:15 GMT and ECB Chief Economist Lane at 09:00 GMT, and both have a strong survey to point to if they want to argue for another hike. The ECB's next decision is on October 29, one day after the Fed's, so its policymakers will vote with the Fed's decision already known.
Germany's governing coalition is also arguing in public after losses in two state elections, one more reason for caution on the Euro even on a day of good data. In the US, weekly jobless claims are due on Thursday at 12:30 GMT, forecast at 201K, and a jump in claims would be the quickest way to cool bets on an October Fed hike.
Levels and bias
Resistance: 1.1400 broke on Wednesday, and 1.1450 held as the floor from September 16 until Tuesday. Above that, 1.1500 capped every session from September 17 to Monday.
Support: 1.1350 comes first, and both Wednesday's low and the late-July low are just above it. Past that, the late-June low just above 1.1300 is the next stop.
Bias: Short below 1.1450, with objectives at 1.1350 and 1.1300. The daily Stochastic Relative Strength Index (Stoch RSI) is down to near 8, deep in oversold territory, so bounces may come before the objectives do. A daily close above 1.1500 takes the short off the table.
EUR/USD daily chart
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















