Week ahead – US payrolls report and AI earnings to keep investors on edge
- After the Fed decision, NFP report awaited for more rate hike clues.
- Employment also on the agenda in Canada and New Zealand.
- Chinese trade and Japanese wage data to be watched too.
- But Iran and AI headlines to remain in driver’s seat for risk sentiment.
Fed confuses the markets
With the Fed still pondering how soon it would be appropriate to raise interest rates, the July jobs report looks set to take centre stage in a week where little else is likely to attract much attention. Although with tensions in the Middle East remaining high and blockbuster earnings struggling to stop the bleeding on Wall Street, volatility isn’t about to ebb.
One recent source of volatility is uncertainty about the Fed policy path, with the July decision only adding to the doubts rather than offering clarity. Fed Chair Kevin Warsh’s resolute stance on abandoning forward guidance has brought on an era of mixed messages about what the Fed intends to do next.
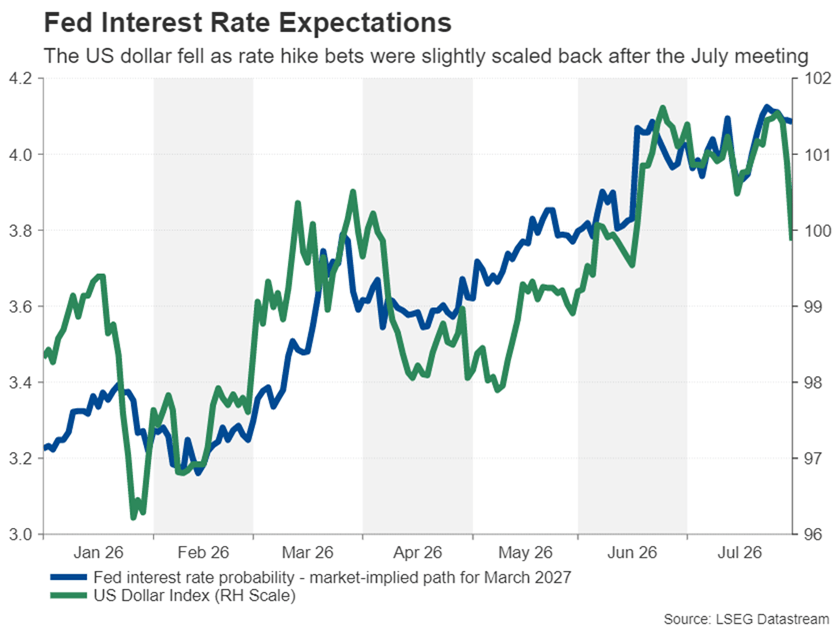
On the one hand, Warsh appeared to be setting the stage for a September rate hike, on the other, he seemed to stop short of signalling that higher rates are necessary to bring inflation back towards the 2% target.
Crucially, despite all the talk about the importance of the Fed achieving its price goal, a September rate hike is now only about 65% priced in compared to being fully baked in prior to the meeting. Warsh seems to be hoping that by talking tough on inflation, it will magically hit the target by itself. Bond markets weren’t impressed, pushing the 30-year Treasury yield to the highest since 2007.
Will July jobs report seal a September hike?
With the upcoming week bringing a plethora of job indicators, September rate hike odds are likely to continue swinging back and forth before culminating with the all-important nonfarm payrolls report.
The ISM business surveys will also provide vital updates on the economy. The ISM manufacturing PMI will kick off the week on Monday, and the services PMI follows on Wednesday. Both sectors have so far been immune to the war in the Middle East, with the only notable impact being the jump in the respective prices indices.
Investors will be watching whether there was any resurgence in price pressures in July when the US-Iran ceasefire was broken and traffic through the Strait of Hormuz collapsed again.
June factory orders out on Tuesday is the only other non-labour market data of the week, which will be released at the same time as the JOLTS job openings. On Wednesday, the ADP private employment report will be gauged for any insights into Friday’s official numbers, while Thursday’s Challenger Layoffs for July will be the next piece of the jobs puzzle.
On Friday, all eyes will be on the payrolls data. Following June’s disappointing print of 57k, analysts are forecasting a slight improvement of 91k jobs. The unemployment rate is expected to have ticked up, however, from 4.2% to 4.3%. Any reading above 100k would likely boost confidence in the labour market, fuelling rate hike bets for September.
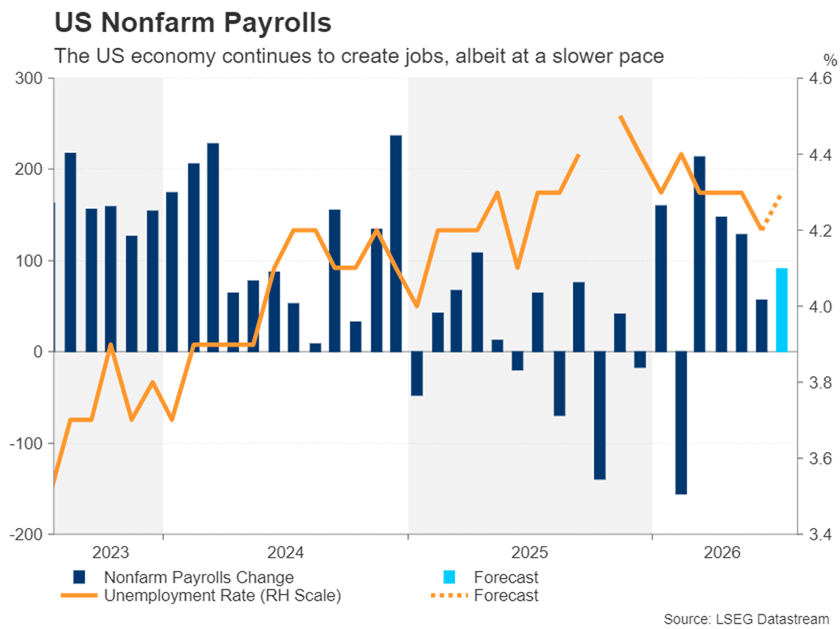
However, a second straight month of a negative surprise would raise question marks about the strength of hiring, leading investors to pare back rate hike expectations.
Can chip stocks stage a rebound?
Yet, any signs of labour market weakness are unlikely to be seen as a reason to worry about the broader economy. After all, even Kevin Warsh thinks that the economy is showing “impressive resilience”, and the strong earnings growth enjoyed by most Wall Street firms in the second quarter is evidence of this. Hence, a soft jobs report would be positive for risk appetite, as September bets would decline further, though this would come at the expense of dollar strength.
Nonetheless, stellar earnings, especially at a time of elevated geopolitical and trade frictions, haven’t been enough to ease concerns about an AI bubble. Doubts about overinvestment in the AI sector and how all this spending is being financed continue to dog sentiment around AI-related stocks. And with stretched valuations, investors have set the bar for both actual and expected earnings very high.
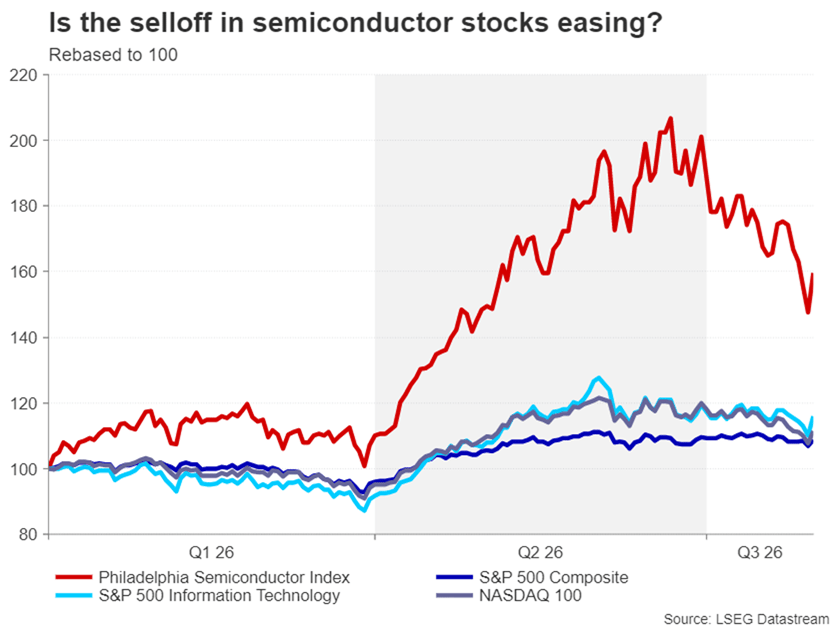
But the selloff may have been overdone, particularly in semiconductor stocks, and a rebound is underway. Considering that volatility was partly exacerbated due to the questionable regulation of South Korea’s stock market where chip giants SK Hynix and Samsung are listed, a further recovery could be on the cards if the upcoming AI earnings continue to point to robust revenue growth.
The highlights will be Palantir Technologies on Monday, SpaceX and Advanced Micro Devices on Tuesday, and Sandisk Corporation and Western Digital on Wednesday.
Divergent rate outlooks for BoC and RBNZ
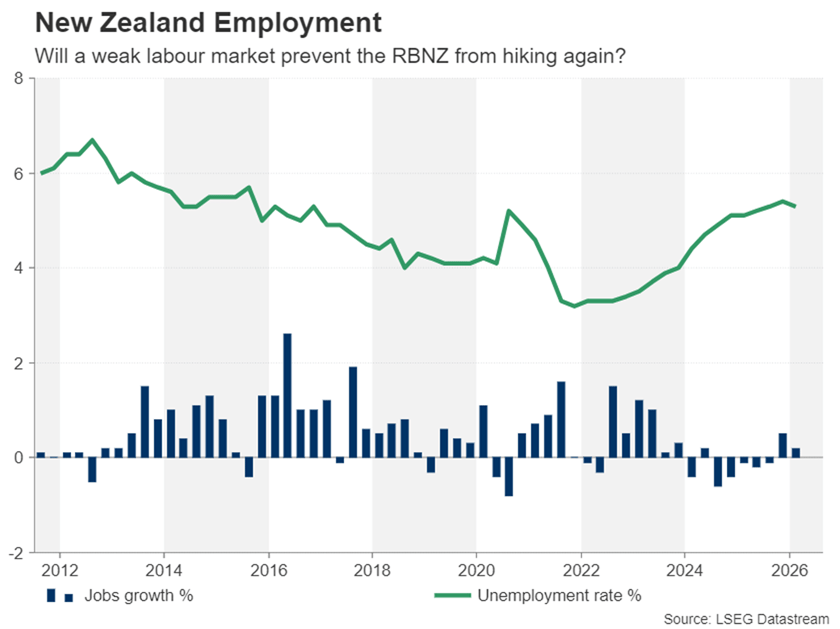
Switching back to economic data, employment will take the spotlight in Canada and New Zealand. Although both countries have seen their jobless rates trend north since 2023, the inflation picture has been somewhat different. The Reserve Bank of New Zealand raised interest rates earlier in July to tackle surging inflation, which hit 4.1% y/y in the second quarter. However, inflationary pressures have been more benign in Canada, and the Bank of Canada may well end up being the only major central bank not to hike interest rates during the Middle East conflict.
The July employment figures due Friday are unlikely to significantly alter the rate outlook for the BoC, with any impact on the Canadian dollar probably being confined to a knee-jerk reaction, even if there are surprises.
However, New Zealand’s jobs data out on Wednesday could be more vital for RBNZ rate hike expectations. A second rate hike is fully priced in for the RBNZ at its September meeting. But with the labour market showing only tentative signs of recovery, any fresh deterioration in Q2 could prompt the RBNZ to delay further tightening, weighing on the New Zealand dollar.
Yen enjoys intervention lift as BoJ stands pat
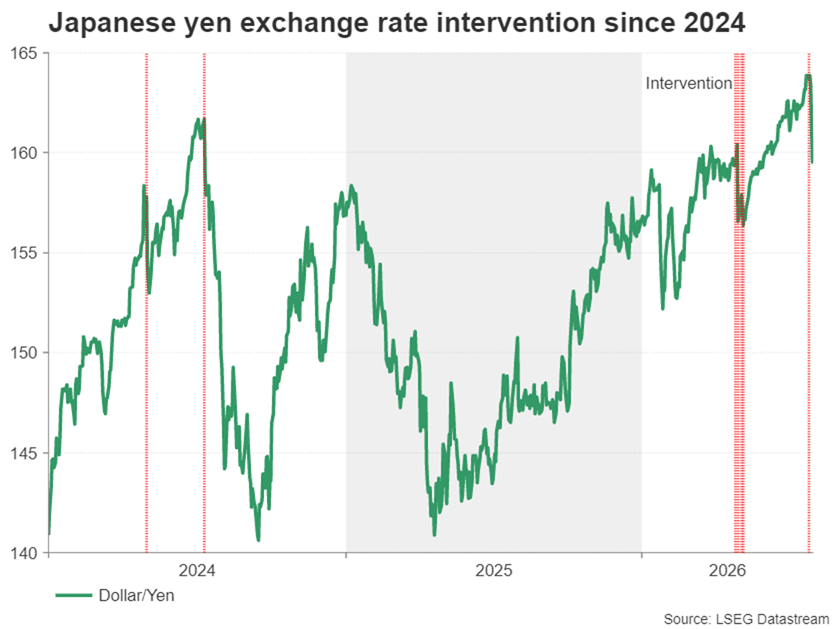
After the yen repeatedly tested the 164 per dollar level, the Japanese government finally decided to intervene on Thursday, boosting it to the 158.00 per dollar level. The intervention came despite the yen already being offered some relief from the Fed’s mixed signals on the likelihood of rate hikes. Not that the Bank of Japan necessarily did a better job as it kept rates unchanged. But there was a visible hawkish tilt, as policymakers sounded more worried about underlying inflation overshooting their 2% target.
Wage growth and household spending figures due Wednesday and Friday, respectively, could help build the case for the BoJ to bring forward its next rate hike from December, as currently anticipated by investors, to September or October.
The Bank of Japan sees sustained wage increases backed by strong household spending as key to hitting its inflation target sustainably, so more progress on this front would be positive for the yen. Nevertheless, the risk of further intervention remains high as hot US data could easily send the yen spinning again.
In addition, Middle East headlines could jolt markets at any point, as the US and Iran seem far from agreeing to any new talks, so further attacks are more likely than a pause. Chinese trade figures released on Friday will also be important for setting the market tone, as investors assess the effects of the five-month-old war on the major economies.
Author

Mr Boyadjian graduated from the London School of Economics in 1999 with a BSc in Business Mathematics and Statistics.