Gold and the Dollar await the Fed’s meeting
The week ahead features a range of important events on the economic calendar, most notably the meetings of the Federal Reserve (Fed) and the European Central Bank (ECB). With no news of major new American attacks on Iran over the weekend, for now the conflict in the Gulf is out of focus as traders concentrate on monetary policy and GDP from various countries. This article looks ahead at the releases in the next few days then briefly analyses the charts of gold and euro-dollar.
The Bank of Canada (BoC), Reserve Bank of New Zealand (RBNZ), Fed, ECB and Bank of Japan (BoJ) are all meeting over the next few days with the BoC and RBNZ both expected to hike rates. The probability of the Fed holding is very high at around 90%; for now, participants are pricing in hikes by both the Fed and ECB in December. The BoJ’s meeting has perhaps the most intrigue surrounding it given the disagreement among the board about the pace of hiking, so it’d be possible to see some indication of another hike towards the end of the year or early 2027.
At least one more hike by the Fed before the end of the year is favourable with a cumulative probability of around 80% according to CME FedWatch:
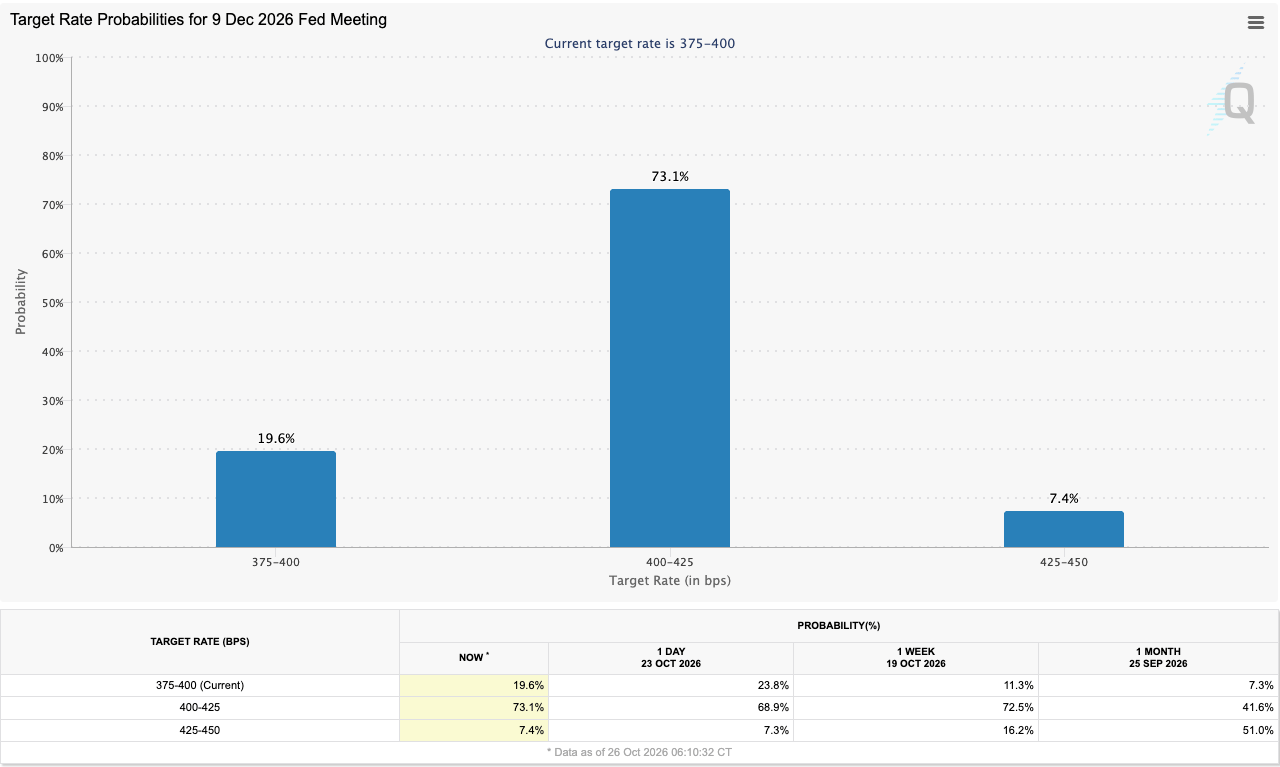
Although there was a brief surge in the likelihood of a hike this week immediately after 14 October’s stronger inflation, with hold and single hike briefly being about 50-50, this subsided quite quickly. Kevin Warsh’s recent comments about economic conditions matching expectations overall and an overall slower job market reduce the pressure on the Fed to hike quickly although inflation might continue to rise given oil’s recent gains.
In the eurozone traders have concentrated on yields from bonds and civil instability in France over recent weeks with the euro suffering against most currencies. Friday’s GDP data, eurozone-wide and from various major individual countries, is expected to be somewhat weaker on the whole. Global political news shifted to the results of Brazilian and Serbian elections on Monday while traders are looking ahead to the British budget on Wednesday and of course the American midterms next week.
Gold back at $4,000 but immediate continuation doubtful
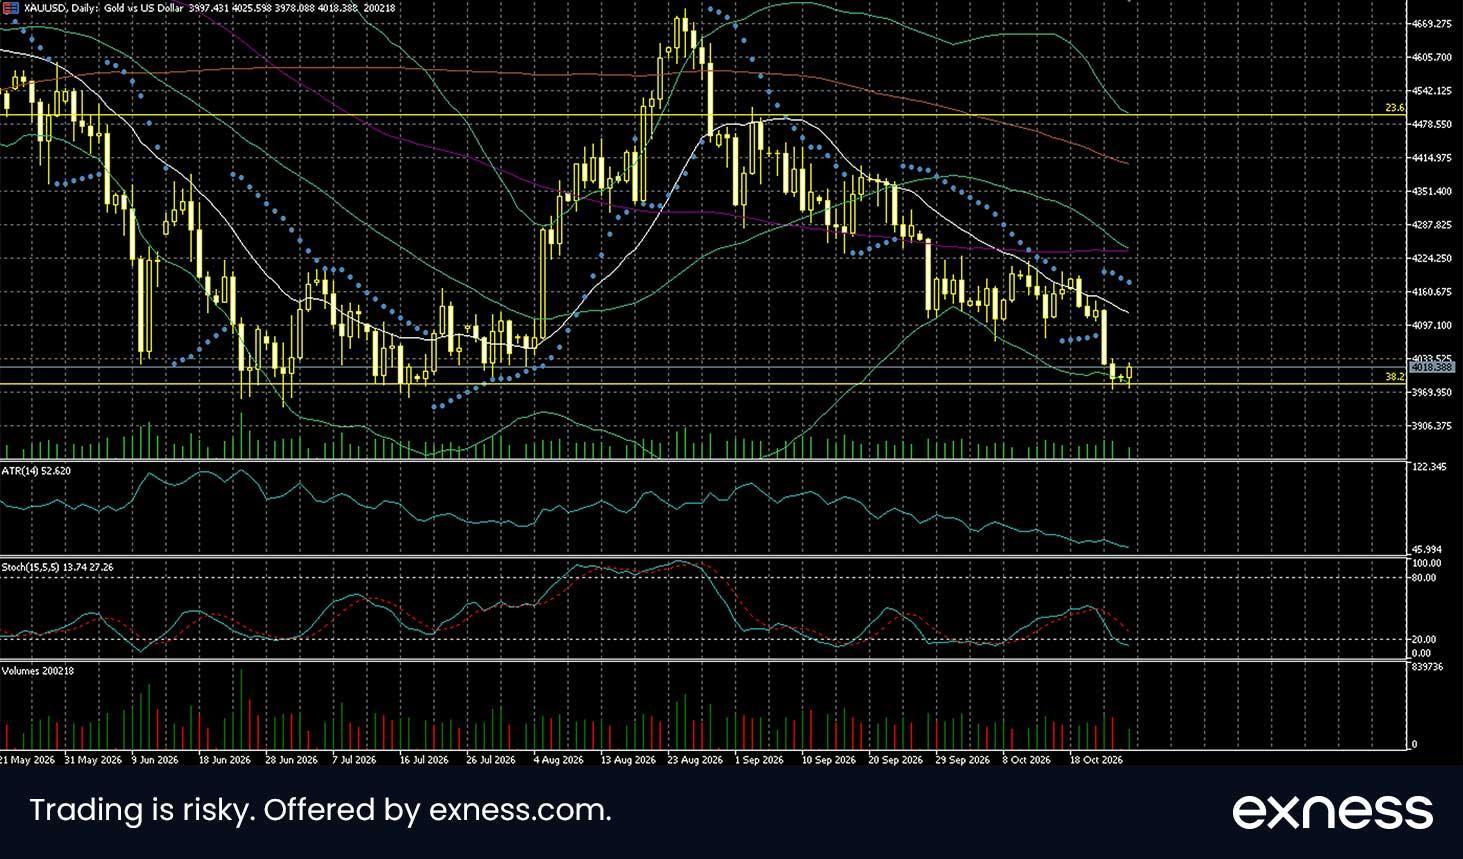
After a relatively large intraday loss on 22 October, gold has held around $4,000 as participants await the Fed’s meeting on Wednesday and the possibility of hostilities in the Gulf heating up again. With no significant changes to expectations for American rates by the end of the year in recent days, the focus is also on American GDP and PCE coming on Thursday 29 October.
$4,000 seems to be a strong support for now at least as the area of summer’s triple bottom and only slightly below the 38.2% weekly Fibonacci retracement. Now that the slow stochastic signals oversold and the price is close to selling saturation from Bollinger Bands, a bounce might be more likely than a strong push lower in the runup to the Fed’s meeting.
$4,100 would be a possible short-term target slightly below the 20 SMA. Volume is likely to remain relatively low in the next couple of days as most participants avoid large volumes ahead of major news and data. Advance GDP for last quarter on Thursday 29 October is also a key release given that expectations of around 3.2% are quite high considering the context from jobs and inflation.
Key data this week
Bold indicates the most important releases for this instrument.
Tuesday 27 October
● 12.30 GMT: American durable goods (September) – consensus 1.5%, previous nil
Wednesday 28 October
● from 18.00: meeting and press conference of the Federal Reserve – consensus 3.75-4% (no change)
Thursday 29 October
● 12.30: American GDP (Q3 advance) – consensus 3.2%, previous 2.2%
● 12.30: American annual headline PCE (September) – consensus 3.6%, previous 3.4%
● 12.30: initial jobless claims (24 October) – consensus 200,000, previous 194,000
Euro-dollar holding around $1.12 ahead of central banks’ meetings
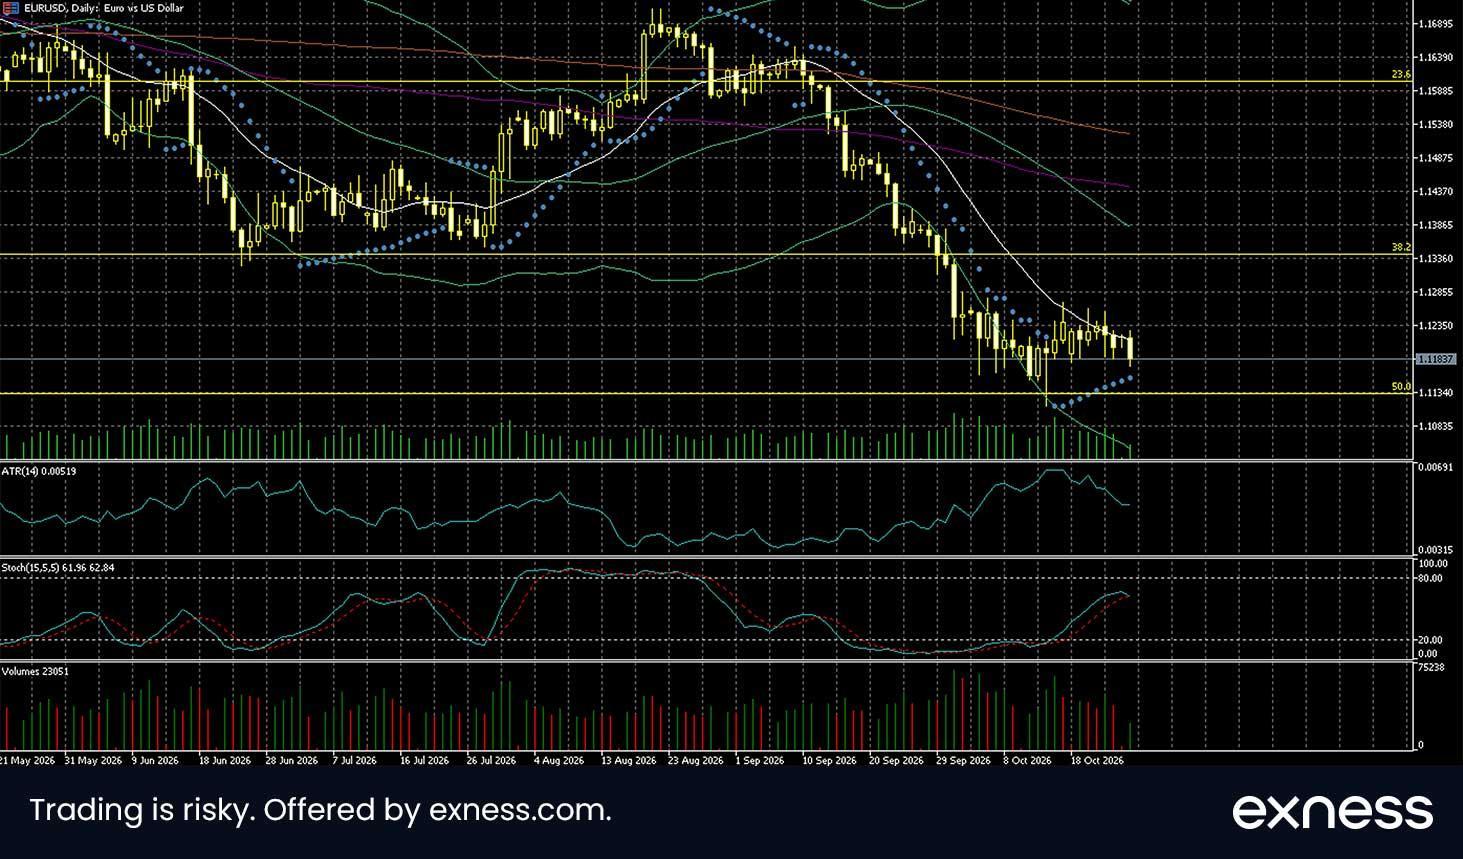
The euro has suffered in most of its pairs in recent weeks as yields from French bonds increased above 5% and have held near there while markets are also worried about France’s fiscal situation. The ECB is likely to hold rates on Thursday 29 October but a hike seems possible in December. The current differential then is likely to remain 1.25-1.5% in favour of the dollar for the next couple of months.
$1.12 seems to be a support with the price having lacked momentum to push clearly below there in the last fortnight despite stronger American inflation and the situation in France. The large tail of 14 October’s candlestick suggests demand in this zone. Given the fundamental situation, though, possible gains in the next few days are unlikely to be more than a short-term bounce unless upcoming data are particularly surprising.
With no sign of saturation as the slow stochastic is slightly closer to neutral than overbought, the price could bounce to around $1.13 or possibly slightly higher before resuming the overall downtrend. However, this depends on a variety of data due in the next few days, so it’s important to watch the reaction to GDP, inflation/PCE and, to a lesser extent, the German job report as well as the central banks’ meetings.
Key data this week
Bold indicates the most important releases for this instrument.
Tuesday 27 October
● 12.30 GMT: American durable goods (September) – consensus 1.5%, previous nil
Wednesday 28 October
● from 18.00: meeting and press conference of the Federal Reserve – consensus 3.75-4% (no change)
Thursday 29 October
● 12.30: American GDP (Q3 advance) – consensus 3.2%, previous 2.2%
● 12.30: American annual headline PCE (September) – consensus 3.6%, previous 3.4%
● 12.30: initial jobless claims (24 October) – consensus 200,000, previous 194,000
● from 13.15: meeting and press conference of the European Central Bank – consensus 2.5% (deposit rate; no change)
Friday 30 October
● 6.30: French quarterly GDP (Q3, preliminary) – consensus 0.1%, previous nil
● 7.45: French annual headline inflation (October, preliminary) – consensus 3.2%, previous 3.1%
● 8.55: German unemployment (October) – consensus 6.4%, previous 6.4%
● 9.00: German quarterly GDP (Q3, flash) – consensus 0.1%, previous 0.3%
● 10.00: eurozone-wide quarterly GDP (Q3, flash) – consensus 0.2%, previous 0.6%
● 10.00: eurozone-wide unemployment (September) – consensus 6.4%, previous 6.4%
● 13.00: German annual headline inflation (October, preliminary) – consensus 3%, previous 3.3%
The opinions in this article are personal to the writer; they do not represent those of Exness. This is not a recommendation to trade.
Author

Michael Stark
Exness
Michael has been investing since 2007 and trading CFDs since 2013. He favors considering both fundamental and technical analysis where possible, with a focus on swing and position trading.

















