The British Pound Sterling is hawkish for all the wrong reasons
- GBP/USD gave back its entire post-CPI rally to close at session lows.
- BoE hike bets are building on energy inflation, not growth.
- Next week stacks UK CPI, the labour market report, and the BoE inside two days.

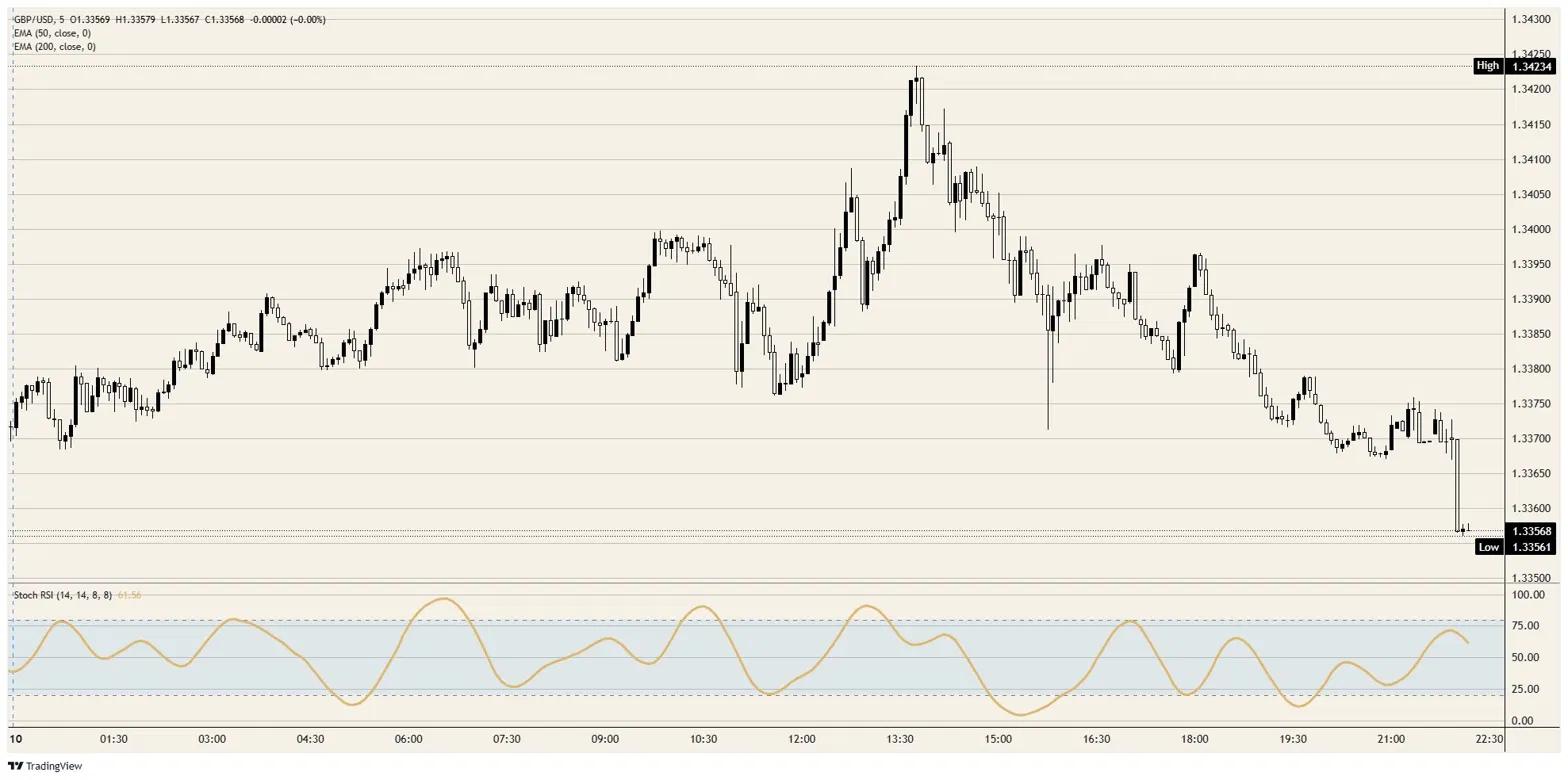
Pound Sterling was handed a gift on Wednesday and dropped it within the hour. A soft core reading inside the US Consumer Price Index (CPI) report knocked the Dollar back just long enough for GBP/USD to reclaim the 200-day Exponential Moving Average (EMA) around 1.3400, tagging session highs just beyond it before the entire move was methodically sold through the US afternoon to a close at the day's lows near 1.3350. A currency that cannot hold a rally on objectively helpful data is making a statement about what sits underneath, and what sits underneath Sterling is a rate story that looks hawkish on the screen and stagflationary in the detail.
Hawkish, but not the good kind
The repricing toward Bank of England (BoE) hikes is real enough that it already has a vote, with the last Monetary Policy Committee (MPC) decision splitting eight to one and the lone dissenter calling for a hike rather than a cut. The trouble is the company that vote keeps. The Strait of Hormuz disruption has kept Crude Oil elevated for months, forecasters see UK inflation climbing toward 3.6% this year against a last print of 2.8%, and meanwhile unemployment is holding at 5%, the number of payrolled employment keeps shrinking, and Friday's monthly Gross Domestic Product (GDP) release at 06:00 GMT is forecast to show the economy contracted 0.1% in April.
A committee drifting toward hikes while output shrinks is not projecting strength, it is admitting the energy shock has left it without good options, and currencies tend to punish that variety of hawkishness rather than reward it.
The gilt market is doing the talking
The cleaner read on Sterling's predicament still comes from the bond market, where 10-year gilt yields spent much of May at or above 5%, territory last visited during the financial crisis. That is a risk premium, not a growth signal, pricing in energy costs, fiscal arithmetic that deteriorates with every hike, and a political backdrop where pressure on the Prime Minister's position has become a tradeable variable. The pattern where higher yields fail to attract currency inflows is the classic fiscal-stress signature, and Wednesday's failed rally at the 200-day EMA was a textbook example of it capping the price.
Flying blind into a stacked week
The domestic calendar offers Sterling nothing of consequence for the rest of this week beyond that second-tier GDP print, which leaves the pair trading US data it cannot influence: Producer Price Index (PPI) figures Thursday at 12:30 GMT, with consensus near 6.4% YoY, and Friday's University of Michigan (UoM) survey at 14:00 GMT, where one-year inflation expectations last sat close to 4.8%. CME FedWatch has next Wednesday's Federal Reserve (Fed) hold roughly 98% priced, with about 70% odds of at least one hike by the December meeting.
Then the calendar flips violently, as UK CPI lands next Wednesday at 06:00 GMT, twelve hours before the Fed decision, followed by the labour market report and the BoE itself on Thursday, with the rate call due at 11:00 GMT. Sterling's June will effectively be decided inside that 30-hour window.
Levels and bias
Upside: the 200-day EMA around 1.3400 is now the proven ceiling after Wednesday's rejection, with the 50-day EMA close to 1.3450 and the bigger test near 1.3500 behind it. Downside: the early-June base around 1.3300 is first support, and a clean break opens the spring lows near 1.3150 before the BoE has even spoken. Bias: skeptical of Sterling strength into next week. Wednesday confirmed the market is selling rallies, the hawkish repricing raises borrowing costs faster than it raises the currency, and the gilt market still gets the final vote.
GBP/USD 5-minute chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author
Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.