Australian Dollar rebounds as US Dollar steadies in thin holiday trade
- Australian Dollar rebounds toward a 14-month high of 0.6727.
- The RBA board is prepared to tighten policy should inflation not moderate as anticipated.
- FOMC December Meeting Minutes will be eyed on Tuesday for insight into the Fed’s 2026 outlook.
The Australian Dollar (AUD) inches higher against the US Dollar (USD), rebounding toward the 14-month high of 0.6727 on Tuesday. The AUD finds support amid growing expectations of interest rate hikes from the Reserve Bank of Australia (RBA). Volumes are expected to be thin due to the New Year's holiday in Australia.
The Reserve Bank of Australia’s (RBA) December Meeting Minutes signaled growing uncertainty among board members about whether monetary policy remains sufficiently restrictive. The policymakers indicated they stand ready to tighten policy if inflation fails to ease as expected, placing increased focus on the Q4 CPI report due January 28. Analysts note that a stronger-than-expected Q4 core inflation reading could trigger a rate hike at the RBA’s February 3 meeting.
The AUD/USD pair could rise as the US Dollar (USD) could face challenges amid ongoing expectations of two more rate cuts by the Federal Reserve (Fed) in 2026. Traders are likely to focus on the Federal Open Market Committee (FOMC) December Meeting Minutes due later in the day.
US Dollar holds ground despite Fed rate cut bets
- The US Dollar Index (DXY), which measures the value of the US Dollar against six major currencies, is gaining ground and trading around 98.00 at the time of writing.
- The Fed lowered interest rates by 25 basis points (bps) at the December meeting, bringing the target range to 3.50%–3.75%. The Fed delivered a cumulative 75 bps of rate cuts in 2025 amid a cooling labor market and still-elevated inflation.
- The CME FedWatch tool shows an 83.9% probability of rates being held at the Fed’s January meeting, up from 80.1% a week earlier. Meanwhile, the likelihood of a 25-basis-point rate cut has fallen to 16.1% from 19.9% a week ago.
- US Initial Jobless Claims declined to 214K from 224K in the prior week, beating the 223K market forecast. Meanwhile, Continuing Jobless Claims rose to 1.923 million from 1.885 million, while the four-week average of Initial Claims edged lower to 216.75K from 217.5K.
- The US Bureau of Economic Analysis (BEA) released delayed data showing that preliminary US Gross Domestic Product (GDP) Annualized expanded 4.3% in the July–September period. The reading exceeded market expectations of a 3.3% increase and surpassed the 3.8% growth recorded in the previous quarter.
- Bloomberg reported Sunday that China’s Ministry of Finance plans to expand targeted investment in priority sectors, including advanced manufacturing, technological innovation, and human capital development. The announcement followed a year-end meeting outlining next year’s fiscal policy priorities. Any impact on China’s economy could affect the AUD, given Australia’s close trade ties with China.
- Australia’s headline inflation rose to 3.8% in October 2025 from 3.6% in September, remaining above the RBA’s 2–3% target range. As a result, markets are increasingly pricing in a rate hike as early as February 2026, with both the Commonwealth Bank of Australia and National Australia Bank projecting a rise to 3.85% at the RBA’s first policy meeting of the year.
- Australia’s Consumer Inflation Expectations rose to 4.7% in December from November’s three-month low of 4.5%, supporting the Reserve Bank of Australia’s (RBA) hawkish stance.
Australian Dollar tests 0.6700 barrier after rebounding from nine-day EMA
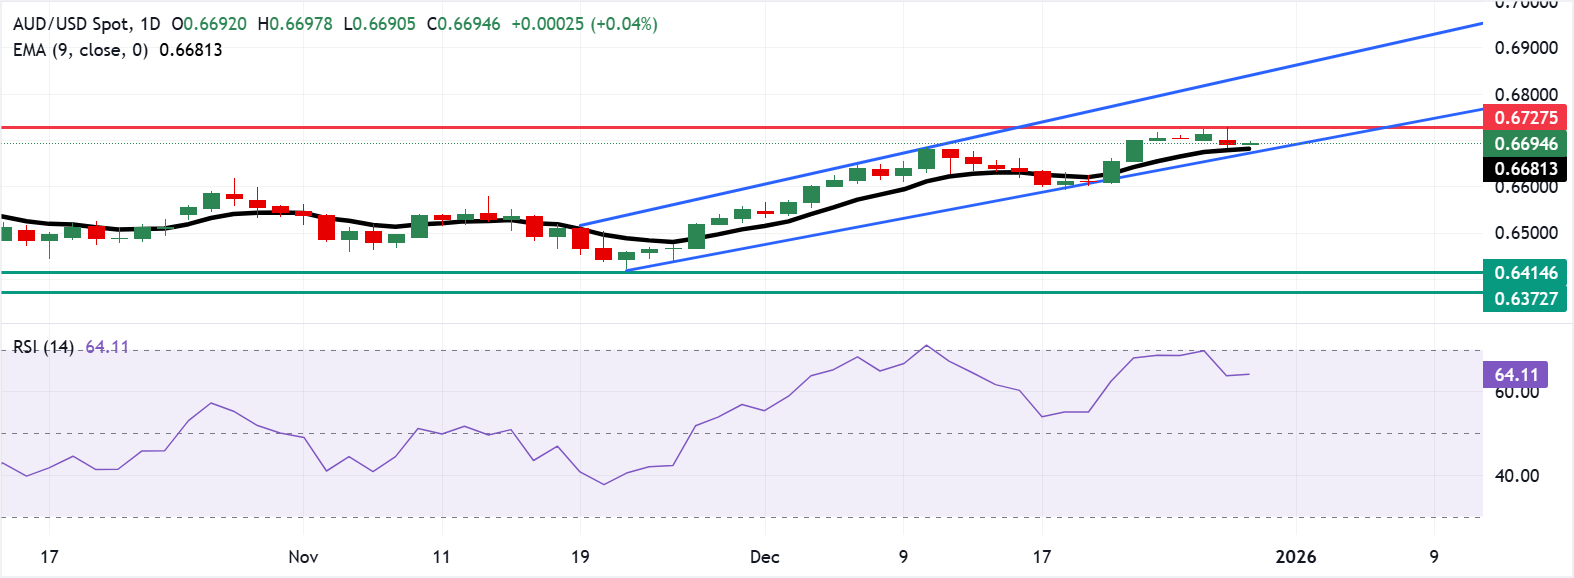
AUD/USD is trading around 0.6690 on Tuesday. The technical analysis of the daily chart indicates that the pair remains within the ascending channel pattern, suggesting a persistent bullish bias. The pair holds above a rising nine-day Exponential Moving Average (EMA), preserving the short-term uptrend. The average continues to advance, keeping a bullish bias in place. The 14-day Relative Strength Index (RSI) at 64.22 signals strong momentum.
After rebounding from a nine-day EMA support, the AUD/USD pair is testing the immediate resistance at the psychological level of 0.6700, followed by the 0.6727, the highest level since October 2024, reached on December 29. The daily tone stays positive above the moving average, which could support the pair to break above the latter and explore the region around the upper boundary of the ascending channel at 0.6840.
On the downside, a break below the nine-day EMA at 0.6681, followed by the lower ascending channel boundary around 0.6670, would open the door for the AUD/USD pair to navigate the region around the six-month low near 0.6414, marked on August 21.
Australian Dollar Price Today
The table below shows the percentage change of Australian Dollar (AUD) against listed major currencies today. Australian Dollar was the strongest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.03% | -0.02% | 0.09% | -0.07% | -0.23% | -0.07% | -0.13% | |
| EUR | 0.03% | 0.00% | 0.13% | -0.05% | -0.20% | -0.05% | -0.10% | |
| GBP | 0.02% | -0.01% | 0.13% | -0.05% | -0.19% | -0.05% | -0.11% | |
| JPY | -0.09% | -0.13% | -0.13% | -0.18% | -0.33% | -0.19% | -0.19% | |
| CAD | 0.07% | 0.05% | 0.05% | 0.18% | -0.14% | -0.00% | -0.06% | |
| AUD | 0.23% | 0.20% | 0.19% | 0.33% | 0.14% | 0.15% | 0.09% | |
| NZD | 0.07% | 0.05% | 0.05% | 0.19% | 0.00% | -0.15% | -0.06% | |
| CHF | 0.13% | 0.10% | 0.11% | 0.19% | 0.06% | -0.09% | 0.06% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Australian Dollar from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent AUD (base)/USD (quote).
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Author

Akhtar Faruqui
FXStreet
Akhtar Faruqui is a Forex Analyst based in New Delhi, India. With a keen eye for market trends and a passion for dissecting complex financial dynamics, he is dedicated to delivering accurate and insightful Forex news and analysis.

















